
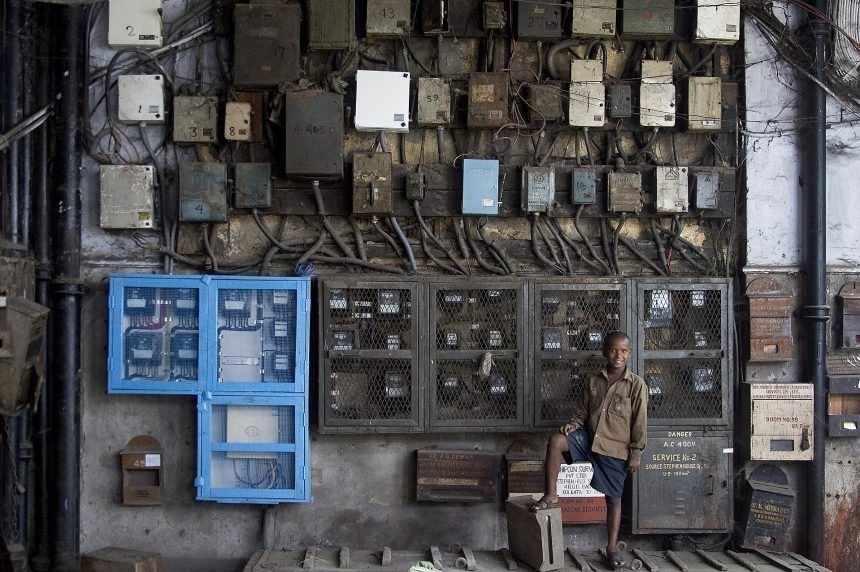
New Delhi – India power distribution companies recorded a profit of roughly 25 billion rupees in financial year 2025, after decades of losses. Aggregate technical and commercial losses fell to 16 per cent from 21.9 per cent four years earlier.
The Revamped Distribution Sector Scheme targets losses of 12 to 15 per cent and the elimination of the gap between average cost of supply and average revenue realised. Projects worth 1.53 trillion rupees have been sanctioned for distribution infrastructure and 1.3 trillion for smart metering.
Why this is the transition story
Distribution companies buy nearly all the renewable power India generates. A loss-making utility with stretched payables cannot credibly sign a twenty-five year purchase agreement, and a developer that doubts payment prices that doubt into its tariff.
Every discussion of renewable cost in India runs through this. Panel prices have collapsed. Counterparty risk has not, and it is a larger component of the delivered tariff than most commentary allows.
The reform on the table
The Electricity (Amendment) Bill 2026 would require cost-reflective tariffs, reducing cross-subsidy and, in principle, strengthening the sector credit profile.
Cost-reflective tariffs are economically correct and politically difficult, because the gap being closed is largely subsidised agricultural and residential supply. Every state government that has tried has discovered the constituency.
The threat from the other direction
Large industrial consumers are moving to captive renewable supply, and they are the customers whose tariffs cross-subsidise everyone else.
As they leave, the utility loses its most profitable load while retaining its least profitable obligations. That dynamic can undo the financial recovery even as the loss numbers improve, and it is the risk least reflected in the current optimism.
Source: Ministry of Power Revamped Distribution Sector Scheme data, discom financial performance for FY25, and the Electricity (Amendment) Bill 2026.